adu-financing
Financing an ADU in 2026: Cash-Out Refinance, HELOCs, and State Grants
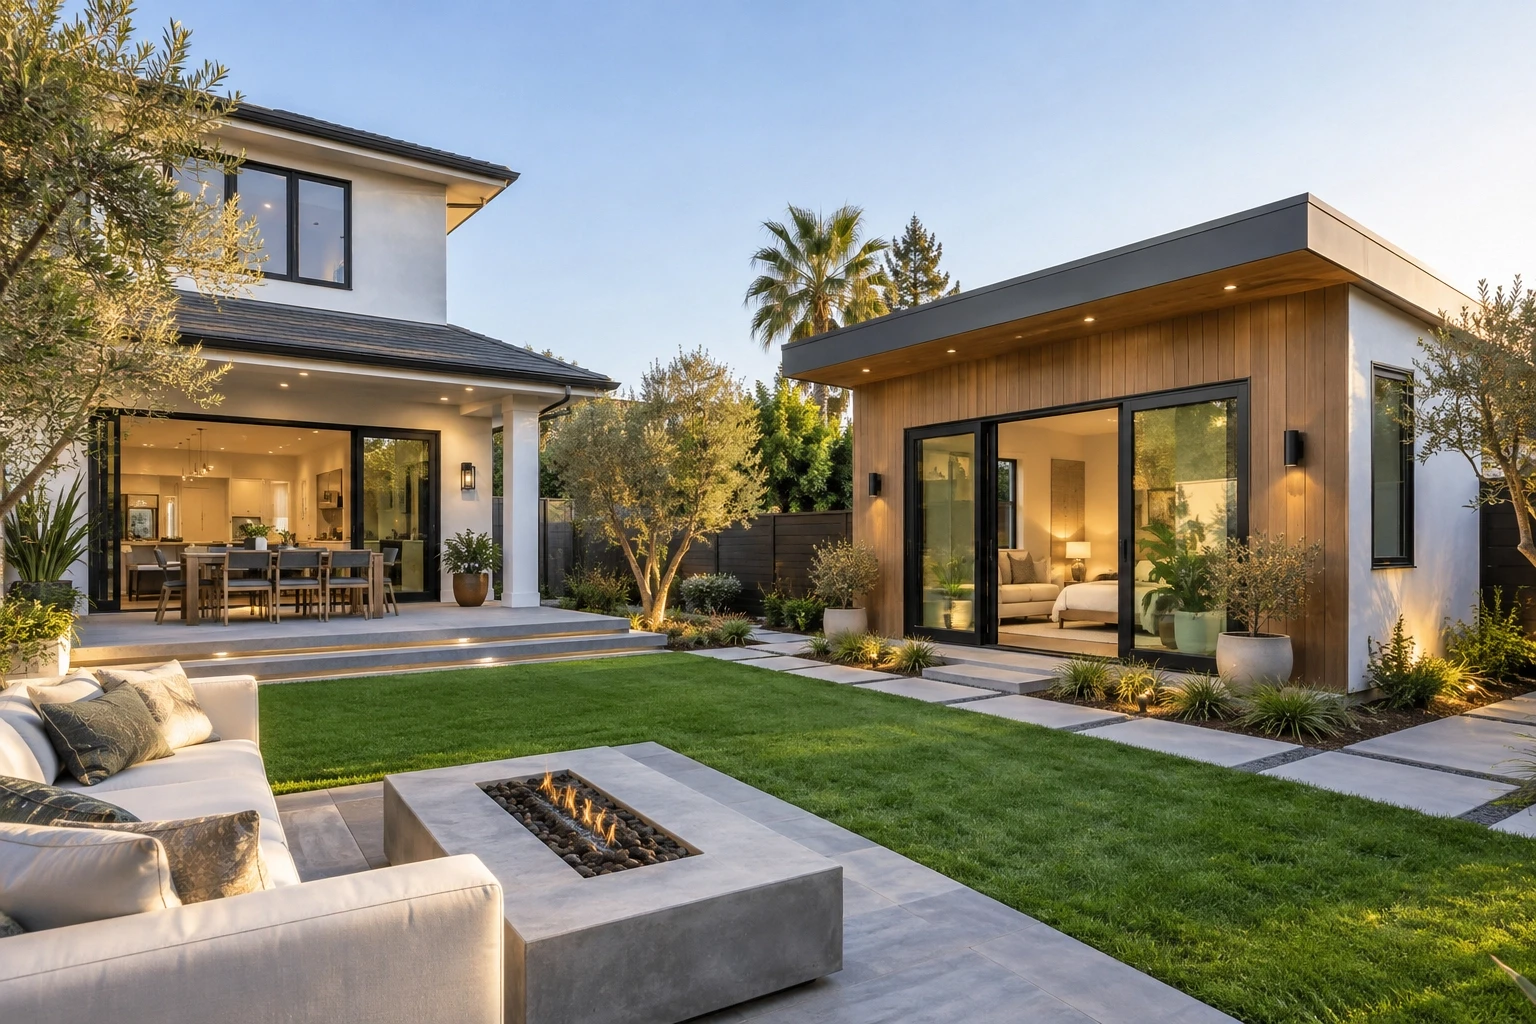
ADU financing 2026 explained: compare cash-out refinance, HELOCs, home equity loans, and California grants to find the right way to fund your ADU.
The main ways to finance an ADU in 2026 include cash-out refinancing, HELOCs, home equity loans, construction financing, savings, and available grant programs. The right option depends on your equity, mortgage terms, income, credit, and total project budget.
California homeowners should plan financing before construction begins. An ADU budget can include design, engineering, permits, site preparation, utility connections, construction, and finishes. Grant programs also have specific eligibility rules and funding limits, so they should never be treated as guaranteed funding.
Understanding each financing option can help you choose a payment structure that fits your budget without taking on more debt than necessary.
Homeowners have several ways to finance an ADU. Some options use existing home equity, while others rely on separate loans, savings, or financial assistance.
The most common ADU financing options include:
Your first step should be understanding the project’s scope and expected cost.
A cash-out refinance can turn part of your home’s existing equity into funds for an ADU. It can provide substantial financing, but it also changes the mortgage secured against your home.
A cash-out refinance replaces your current mortgage with a new mortgage for a higher amount. After paying off the existing loan, the remaining approved funds are provided to you.
For example, assume your home is worth $700,000 and your current mortgage balance is $350,000. You have significant equity, but that does not mean you can borrow the entire $350,000 difference.
The lender will consider factors such as the home’s appraised value, loan-to-value limits, income, credit, existing debts, and loan requirements. Your final borrowing capacity will depend on those factors.
The funds can then be used toward eligible ADU expenses. However, refinancing affects the entire mortgage rather than only the amount needed for the ADU.
The biggest advantage is access to a potentially large amount of capital. This can be useful when an ADU requires substantial upfront funding.
However, refinancing can be less attractive if your existing mortgage has favorable terms. A new loan may have a different interest rate, payment, or closing costs.
Before choosing this route, compare:
A HELOC can provide another way to use home equity without replacing your existing first mortgage. Instead of receiving one large loan, you receive access to a credit line that can be used as needed.
A home equity line of credit allows you to borrow against available equity in your home. You can generally draw funds during a defined draw period, subject to the lender’s terms and approved credit limit.
This structure can fit construction projects because ADU expenses often occur in stages. You may need funds for early project costs before paying for later construction work.
For example, you could use part of the credit line for initial expenses and draw additional funds as construction progresses. You typically pay interest based on the amount borrowed rather than the entire available credit limit.
HELOC terms vary by lender. Some may have variable interest rates, so homeowners should understand how payments could change during the repayment period.
A HELOC for an ADU may make sense if you want to keep your existing mortgage. This can be important when your current mortgage has a rate or terms that you do not want to replace.
A HELOC can also provide flexibility when your construction expenses are spread over several months. You do not necessarily need to borrow the full approved amount immediately.
The main consideration is repayment risk. Because the credit line is secured by your home, you should choose an amount and payment structure that your household budget can comfortably support.
California has offered financial assistance for ADU development through state and local programs. However, funding availability changes, and not every program provides direct money to individual homeowners.
Homeowners should verify current program status before including grant funding in an ADU financing plan.
The California Department of Housing and Community Development provides information about ADU funding sources and local assistance programs. Some programs may support construction, predevelopment, or other qualifying expenses.
The CalHFA ADU Grant Program previously offered up to $40,000 toward eligible predevelopment costs. However, CalHFA states that funds for that program were fully reserved in December 2023. Therefore, homeowners should not assume that the same grant is available for new applications in 2026.
Local programs can have different funding sources and requirements. Some may offer loans, technical assistance, grants, or other forms of support.
This makes it important to search for ADU grants California programs based on your specific city or county rather than relying on an older statewide program.
ADU grant programs can have strict requirements. Depending on the program, eligibility may involve household income, property location, owner occupancy, rental conditions, or project requirements.
Some funding is also distributed to local governments or nonprofit organizations. Those organizations may then administer assistance to eligible homeowners.
Before relying on financial assistance, confirm:
If a grant has not been approved, it is safer to keep a separate financing plan for the project.
Cash-out refinancing, HELOCs, and grants work very differently. Comparing their structure, cost, flexibility, and availability can make the decision easier.
| Financing Option | Structure | Main Benefit | Main Drawback | Best Suited For |
|---|---|---|---|---|
| Cash-out refinance | Replaces existing mortgage | Potentially provides substantial funding | Changes the entire mortgage | Larger ADU projects with significant equity |
| HELOC | Revolving home equity credit line | Flexible access to funds | Rates and payments may change | Projects with staged expenses |
| Home equity loan | Lump-sum second loan | Defined borrowing amount | Adds another secured payment | Projects with a known budget |
| Grant or assistance | Financial support for eligible costs | Can reduce borrowing needs | Limited availability and eligibility | Homeowners who qualify |
There is no universal winner. A homeowner with a favorable first mortgage may prefer a HELOC, while someone seeking a larger lump sum may consider refinancing. A qualifying grant can reduce the amount that needs to be borrowed.
The amount you borrow should reflect the complete project budget rather than the maximum amount a lender offers. Borrowing too little can create problems later, while borrowing more than necessary increases your repayment costs.
Start with construction and then add the other expenses required to complete the project. These can include:
The ADU type also affects the budget. A new detached unit may have different expenses from an attached unit or garage conversion. If you are considering a garage conversion, reviewing the factors that affect garage-to-ADU costs can help you build a more accurate financing target.
Permitting should also be included early. Understanding potential ADU permit expenses can prevent unexpected costs from being left out of your initial budget.
A realistic budget should also include reasonable room for unexpected construction conditions. This does not mean borrowing excessively. It means avoiding a plan that depends on every cost coming in at the absolute minimum.
The best financing option depends on your current mortgage, available equity, project budget, and ability to manage the resulting payment.
ADU financing in 2026 can involve a cash-out refinance, HELOC, home equity loan, construction financing, personal savings, or an available assistance program. The best choice depends on your equity, existing mortgage, financial qualifications, project scope, and repayment goals.
Start by developing a realistic ADU budget and confirming the project’s requirements. Then compare financing options based on their total cost and long-term effect on your household finances.
Once you understand the construction scope and financing amount, planning your ADU project with a qualified remodeling contractor can help you move toward construction with a clearer financial plan.
California has ADU-related funding programs, but availability changes. The CalHFA ADU Grant Program previously offered up to $40,000 for eligible costs, but its funds were fully reserved in December 2023. Always verify current state and local programs before including grant money in your financing plan.
Neither option is automatically better. A HELOC can preserve your existing mortgage and provide flexible access to funds. A cash-out refinance replaces your current mortgage and may provide a larger lump sum. Compare rates, fees, payment terms, and long-term costs.
Yes. You may be able to **finance an ADU without refinancing** through a HELOC, home equity loan, construction financing, savings, or another available loan. Your options depend on your lender, equity, income, credit, and project.
There is no universal equity requirement for every ADU loan. Lenders may consider your home value, existing mortgage balance, income, credit, debts, and applicable loan-to-value requirements. A detailed project budget can help determine how much financing you actually need.